 Analysis by Appwee
Before I decide to take money out early, I treat earned-wage access as a cash-flow tool, not a raise. That distinction is the key to using DailyPay On-Demand Pay well: it can help bridge a timing gap, but the wages are still part of the paycheck I would otherwise receive later. When I keep that in view, the app’s main benefit becomes clearer—more choice about when already-earned pay reaches me, rather than extra money to spend.
The practical question is not simply whether early access sounds useful. It is whether the timing of your bills, the way you handle a shortfall, and your employer’s participation make this particular approach worthwhile. I’d think through those points before relying on it for regular expenses.
Getting Started with DailyPay
First things first, setting up DailyPay On-Demand Pay is a breeze. You simply download the app from the Google Play Store or the Apple App Store, and you’re on your way to financial flexibility. After a straightforward registration process, you link the app to your employer’s payroll system. Not every company is partnered with DailyPay yet, but the list is growing, so it's worth checking!
How It Works
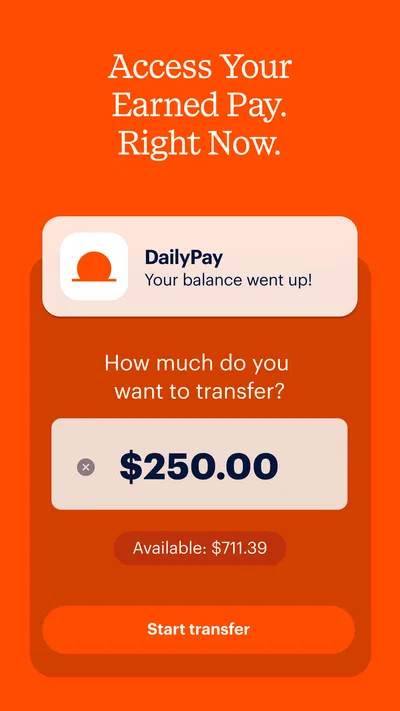
The magic lies in the app’s ability to track your daily earnings. As you work, DailyPay On-Demand Pay calculates how much you've earned each day. You’ll see this amount reflected in the app, and you can choose to transfer it to your bank account whenever you need. It’s like having a virtual piggy bank that you can crack open when unexpected expenses pop up.
Transfers are usually instant, which is a huge relief if you're in a pinch. There is a small fee for each transfer, which might be a downside for some, but for many, the convenience is well worth it. Plus, if you can wait until payday, there’s no fee to transfer your earnings.
Making the timing work in everyday life
For example, say a routine bill is due just before payday and your account balance is tight. I’d first check the amount already available in the app, then compare the cost and timing of a transfer with the likely cost of paying late or going overdrawn. If a transfer avoids a larger, immediate problem, using it once may make sense. If the same bill creates a shortfall every pay cycle, though, early access is only moving the pressure around; I’d treat that pattern as a sign to revisit the bill date, spending plan, or available support rather than making a withdrawal automatic.
A useful habit is to decide what counts as a genuine timing emergency before one happens. That could mean reserving transfers for essential costs with a firm deadline, rather than using available wages for optional purchases simply because the balance is visible. The app can make earned pay feel more spendable than it would if it were still waiting in payroll, so a small personal rule—such as checking the next few days of bills before taking anything—can help preserve the benefit.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
Features and Benefits
One of the standout features is the ability to manage your finances more effectively. With DailyPay On-Demand Pay, you can avoid overdraft fees and late payment penalties. Imagine not having to dip into savings or use a credit card for emergency expenses. It's like a financial safety net that gives you peace of mind.
Budgeting with DailyPay is also a game-changer. Knowing exactly how much you’ve earned and having access to it at any time can help you stick to a budget more effectively. You can plan your expenses around your earnings instead of waiting for the end of the month.
Settings and routines worth checking
When I first set up a service tied to payroll, I’d make sure I understand the employer connection and the account details before depending on it for a deadline. The useful check is not merely whether the app opens, but whether the earnings shown line up with the shifts or work already completed. If the displayed amount seems unexpected, I would pause before transferring and check the relevant records or contact support rather than assuming the balance is ready for a particular bill.
I’d also make a simple payday routine: review any transfers made during the pay period, then look at what remains for the regular payday. That final check matters because an early transfer changes when part of the pay arrives, not the total amount earned. Keeping a note of the reason for each withdrawal can reveal whether the tool is solving occasional timing problems or quietly becoming part of everyday spending.
For faster decisions, I find it helpful to separate the question “Do I need the money now?” from “Can I access it now?” The first is about the bill and alternatives; the second is about the app and transfer choice. Checking them in that order can prevent a convenient option from becoming the default. If the need is not urgent and payday is close, waiting may be the better choice, especially when avoiding a transfer fee is part of the goal.
User Experience
The app itself is user-friendly and intuitive. The design is clean, and navigating through the options is a breeze. You can easily view your earnings, make transfers, and even check your transaction history. Plus, the app provides helpful tips and insights on managing your finances, which is a nice bonus for those looking to improve their financial literacy.
Customer support is responsive, which is always a plus. If you run into any issues or have questions, the support team is just a message away. It’s reassuring to know that help is readily available if needed.
Where it fits among cash-flow alternatives
I see earned-wage access as a middle ground between waiting for scheduled pay and borrowing. Compared with a credit card, it does not create a new line of credit; it lets you draw on pay already earned. Compared with an overdraft, it may help you avoid a shortfall before a payment hits, though the transfer choice and any fee still deserve a careful look. And compared with asking a bill provider for a different due date, it solves the immediate timing issue without changing the underlying schedule. Which is better depends on the situation: a due-date adjustment can be more useful for a recurring mismatch, while early access may suit a one-off gap.
For a reader deciding whether to try it, the first question is whether their employer participates, since that connection is central to the service. The next is whether the app’s available earnings and transfer timing fit the real deadline they are facing. I would not plan around a particular transfer until I had checked what the app currently shows and understood the cost of the option I’m choosing.
Who Can Benefit?
DailyPay On-Demand Pay is ideal for anyone who struggles with the traditional two-week waiting period for paychecks. Whether you're living paycheck to paycheck or simply want more control over your cash flow, this app can provide the flexibility you need. It’s also a fantastic tool for those who are just starting to manage their own finances and want to avoid debt traps.
Employers also benefit by offering this service. It can be a significant perk in employee retention and satisfaction. Who wouldn’t want to work for a company that provides more financial control and peace of mind?
When another approach may be better
I’d be cautious about making this a routine substitute for a buffer in a bank account. If every pay period requires an early transfer to cover ordinary spending, the app may make the shortfall easier to manage without making it smaller. In that situation, a basic review of recurring bills and due dates—or help from a qualified financial counselor—may address the pattern more directly. Someone who prefers not to manage timing decisions, or who has no participating employer, is unlikely to get much practical value from the app.
It is also worth remembering that access to earned pay does not remove the need to plan for the rest of the pay cycle. Before choosing a transfer, I would check what essential expenses remain and leave enough room for them. The most helpful use is often narrow: cover a necessary expense that falls awkwardly between paydays, then return to the normal schedule rather than treating an early transfer as a standing spending allowance.
A Few Considerations
While DailyPay On-Demand Pay offers many advantages, it’s essential to use it wisely. The temptation to withdraw funds frequently can lead to a cycle of dependency. It’s crucial to remember that this is not additional income but a way to access what you've already earned. Developing a solid budgeting plan can help you make the most of this tool without falling into financial mismanagement.
Also, the app’s effectiveness depends on your employer’s participation. Not all companies are on board yet, so it's worth checking if your employer is part of the network before getting too excited.
What to expect before relying on it
DailyPay is a free finance app from DailyPay Inc, and it has a 4.7 average from around 215,000 ratings. That reception suggests many users find the idea useful, but ratings cannot tell me whether it will suit a particular employer’s payroll setup or personal budget. It has over a million installs, is rated for Everyone, and version 44.0.0 is listed for devices running Android 9 or later. I’d still check compatibility and employer availability before building a plan around it.
One reasonable question is whether every transfer is free. The practical answer is to distinguish transfer choices: the article’s described experience includes a fee for a faster transfer and a no-fee option when waiting until payday. I would check the current choice and its displayed terms in the app before confirming, rather than assuming speed is free. Another question is whether the app adds income; it does not. It changes access timing for wages already earned, so the payday amount should be considered alongside any money taken early.
People also often wonder whether they can use it without an employer connection. Because the service depends on payroll participation, confirming that connection is the first useful step; downloading the app alone does not guarantee access to earnings. If the employer is not supported, a bill-date change, a small savings buffer, or a conversation with the creditor may be more relevant alternatives than repeatedly checking the app.
In conclusion, DailyPay On-Demand Pay is a fantastic app that can revolutionize the way you manage your finances. By providing on-demand access to your earnings, it offers a level of financial freedom that many of us crave. Just remember to use it wisely, and it can be a powerful ally in your journey to financial stability. So, if you're tired of waiting for payday, give DailyPay a try—you might just find it’s the app you didn’t know you needed!
DailyPay On-Demand Pay Pros and Cons
- Instant access to earned wages.
- User-friendly interface for quick navigation.
- Integrates with numerous payroll systems.
- Secure transactions and data protection.
- Reduces financial stress for users.
- Limited to partnered employers.
- Potential fees for each transaction.
- Requires stable internet connection.
- May encourage spending beyond means.
- Not available in all regions.
DailyPay On-Demand Pay Frequently Asked Questions
What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is a financial app that allows employees to access their earned wages before the traditional payday. Users can transfer their available earnings to their bank account with just a few taps. The app provides a real-time view of your earned income, enabling greater financial flexibility and control.
Is DailyPay On-Demand Pay safe to use?
Yes, DailyPay On-Demand Pay is designed with user security in mind. It employs advanced encryption and secure data management practices to protect your personal and financial information. Additionally, the app complies with industry standards and regulations, ensuring a safe and reliable user experience.
Are there any fees associated with using DailyPay?
While DailyPay does not charge a subscription fee, there may be small transaction fees for transferring your earnings. These fees are clearly explained within the app and typically vary depending on the speed and method of transfer you choose. It's important to review these costs before proceeding with any transactions.
Can anyone use DailyPay On-Demand Pay?
DailyPay On-Demand Pay is available to employees of companies that have partnered with DailyPay. If your employer offers this service, you can easily sign up and start using the app. Check with your HR department or the DailyPay website to see if your company is a participating partner.
How quickly can I access my earnings with DailyPay?
With DailyPay, you can typically access your earned wages instantly or within a few business days, depending on the transfer method you choose. The app offers options for immediate transfers for a nominal fee or standard transfers that may take longer but are often free. This flexibility allows you to manage your funds according to your needs.
Gallery